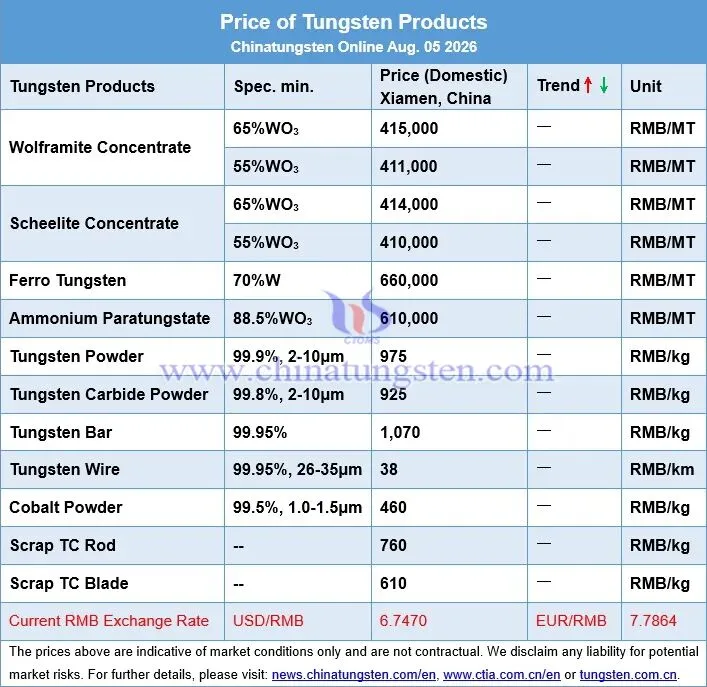
China’s tungsten market remained in a tug-of-war on August 5, 2026. Concentrate, APT, powder and ferrotungsten were broadly stable, while cobalt powder eased to RMB 460/kg.
China’s tungsten market remained in a tug-of-war between bullish and bearish forces on August 5, 2026. According to Chinatungsten Online, trading was still driven mainly by immediate needs, while buyers waited for industry price forecasts and major tungsten producer long-term contract guidance.
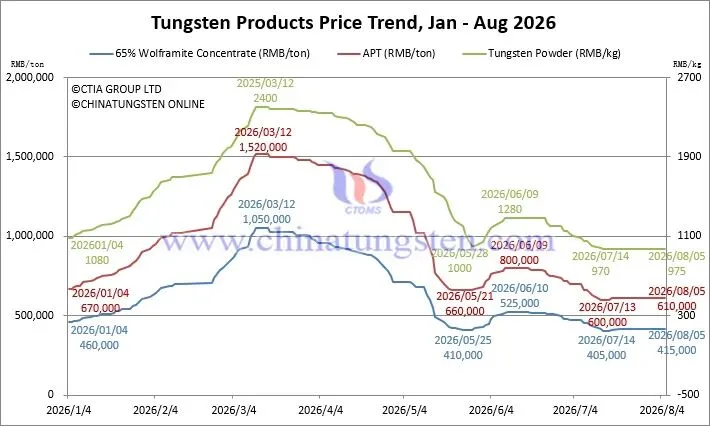
Market overview: concentrate and APT hold, transactions stay slow
Tungsten concentrate stayed in a stalemate near RMB 410,000/standard ton for ore with WO3 grade of 55% or higher. Chinatungsten Online also reported a Guangdong mining-company auction: 89 tons of 19.47% scheelite concentrate sold at RMB 349,000/standard ton, and 67 tons of 17.46% scheelite concentrate sold at RMB 337,400/standard ton.
APT remained cost-supported but slow to transact, which pressured smelter operating rates. Domestic APT was quoted around the RMB 600,000/ton mark, while European APT stayed much higher at USD 3,000–3,279/mtu, equivalent to about RMB 1.792–1.959 million/ton in the source text.
Powder demand remains weak; cobalt powder moves lower
Tungsten powder and tungsten carbide powder markets stayed sluggish because downstream users and traders were still buying for rigid demand only. The price board listed tungsten powder at RMB 975/kg and tungsten carbide powder at RMB 925/kg.
Cobalt powder was quoted at RMB 460/kg, down from the RMB 465/kg level seen in recent updates. Weak demand momentum in new energy and cemented carbide reduced incremental support and kept downward pressure on cobalt-linked carbide grades.
Price table — August 5, 2026 (Chinatungsten Online)
The following table summarizes domestic Xiamen, China price references and international ranges reported by Chinatungsten Online on August 5, 2026. The source board listed USD/RMB 6.7470 and EUR/RMB 7.7864.
| Product | Price | YTD Change |
|---|---|---|
| 65% WO3 wolframite concentrate | RMB 415,000/ton | Stable on the day |
| 55% WO3 wolframite concentrate | RMB 411,000/ton | Stable on the day |
| 65% WO3 scheelite concentrate | RMB 414,000/ton | Stable on the day |
| 55% WO3 scheelite concentrate | RMB 410,000/ton | Stable on the day |
| Ammonium paratungstate (88.5% WO3) | RMB 610,000/ton | Cost-supported |
| European APT | USD 3,000–3,279/mtu (≈ RMB 1,792,000–1,959,000)/ton (equiv.) | International market tight |
| Tungsten powder (99.9%, 2–10um) | RMB 975/kg | Demand sluggish |
| Tungsten carbide powder (99.8%, 2–10um) | RMB 925/kg | Demand sluggish |
| Cobalt powder (99.5%, 1.0–1.5um) | RMB 460/kg | Downward pressure |
| 70% W ferrotungsten | RMB 660,000/ton | Low activity |
| European ferrotungsten | USD 180–195/kg W (≈ RMB 850,000–921,000)/ton (equiv.) | Recent correction |
| Tungsten bar (99.95%) | RMB 1,070/kg | Stable on the day |
| Tungsten wire (99.95%, 26–35um) | RMB 38/km | Stable on the day |
| Scrap tungsten carbide rod | RMB 760/kg | Wait-and-see market |
| Scrap tungsten carbide blade | RMB 610/kg | Wait-and-see market |
Source: Chinatungsten Online · YTD = Year-to-date change from Jan 1, 2026 · WoW = Week-on-week
What this means for carbide tool buyers
- WC powder at RMB 925/kg keeps carbide rod replacement cost sensitive even when tungsten concentrate and APT appear stable.
- Cobalt powder at RMB 460/kg may lower pressure for some grades, but weak demand also signals cautious downstream production.
- Domestic and European APT remain structurally divergent, so export tool buyers should avoid applying one regional raw-material signal globally.
- Scrap tungsten carbide rod at RMB 760/kg shows recycling-linked costs are not collapsing, even with weak spot transactions.
- For custom carbide drills and end mills, confirm whether a quote is based on current rod inventory or new powder and rod replacement cost.
Procurement note
Use the August 5 stabilization window to update carbide tool budgets, but keep quote validity tied to actual production schedules. For repeat tools, send diameter lists; for custom tools, include drawings, work material, coating and annual quantity.
Carbide tools from our Changzhou factory
Factory-direct solid carbide coolant drills for deep holes, stable chip evacuation and heat control.
Standard carbide drills for steel, stainless steel, cast iron and general precision holemaking.
Factory-ground carbide end mills for slotting and profiling with coating options for aluminum and steel.
Carbide ball end mills for mold, die, 3D contour and finishing applications.
Corner-radius carbide end mills for stronger cutting edges and stable semi-finishing or finishing.
Outlook
Near-term tungsten direction will depend on industry forecasts, long-term contract prices from major tungsten producers, and whether downstream order volume improves. Without stronger spot demand, negotiations may remain narrow and cautious.
Solid Carbide Direct will continue tracking tungsten concentrate, APT, tungsten powder, tungsten carbide powder, cobalt powder, ferrotungsten and scrap tungsten carbide indicators to help machining buyers plan raw-material-sensitive tooling budgets.
Tags